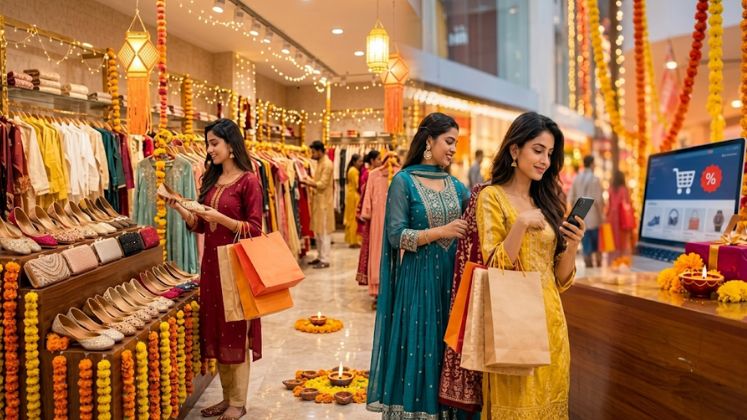
According to a report by retail technology firm Fynd, 50% of online fashion orders in India during September and October 2026 were priced below Rs 1,000, indicating consumers’ preference for affordable purchases during the festive season.
In contrast, products priced above Rs 3,000 accounted for just 11.8% of orders but contributed more than 41% of total sales value. The findings indicate a value-driven consumption pattern, with shoppers balancing budget-conscious purchases against higher spending on selected products.
The report analysed shopping patterns across more than 65 brands on eight marketplaces, including Myntra, Flipkart, Amazon, AJIO, Nykaa, JioMart, Tata CLiQ and Tata CLiQ Luxury.
Average festive discounts increased to 46% in 2026 from 34% in 2025, with nearly half of all orders placed at discounts exceeding 50%. Despite deeper promotions, the spending trends indicate that consumers were responding to deals while remaining conscious of their budgets.
“The festive season unfolded amid higher borrowing costs, elevated fuel prices, global geopolitical uncertainty and continued pressure on household budgets. She added that value emerged as the defining theme of the season,” said Ragini Varma, Chief Business Officer, India, Fynd.
Footwear emerged as the largest online fashion category during the festive period, accounting for 52.7% of total orders and 58.4% of sales value. Its share of orders increased from 33% in 2025.
In comparison, clothing’s share of orders declined from 48% in 2025 to 34.5% in 2026. The shift indicates moderation in discretionary fashion purchases as consumers prioritised products with greater everyday utility.
The geographical distribution of online fashion demand also changed during the festive season. Eastern India accounted for 20.8% of total orders, with West Bengal emerging as the country’s second-largest ordering state.
Tier 2 markets strengthened their contribution, increasing their share of online fashion orders from 19% in 2025 to approximately 35% in 2026.
Tier 1 cities continued to account for around 43% of orders but contributed 56% of gross merchandise value (GMV), indicating higher average spending in larger urban markets.
The marketplace landscape also became more competitive. Myntra and Flipkart continued to lead online fashion sales, but their combined share declined from 89% to 76.8%, as AJIO, Amazon and JioMart gained traction.
Online payments accounted for 56.5% of all orders, with prepaid adoption particularly strong across eastern markets.
The overall return rate stood at 11.8% during the period. Clothing recorded a higher return rate of 14.9%, compared with 10.5% for footwear.